

In recent years, we’ve gotten used to hearing about export controls on dual-use products; drones, semiconductors, machine tools. China has now gone a step further: it’s restricting dual-use materials, and Europe just got a direct taste of it.
On July 24, 2026, China’s commerce ministry MOFCOM banned exports of dual-use materials and products to 14 companies inside the EU, in retaliation for new EU sanctions tied to Russia’s war. Five of the 14 have been named publicly: Rheinmetall (Germany), Lafert Group (Italy), Vigo Photonics (Poland), IHC (Netherlands), and Tatra Trucks (Czech Republic). Nine remain unconfirmed. It’s a small, targeted move, but it’s a preview of the leverage China holds over an entire industrial base.
Wait… Dual-use “minerals”?
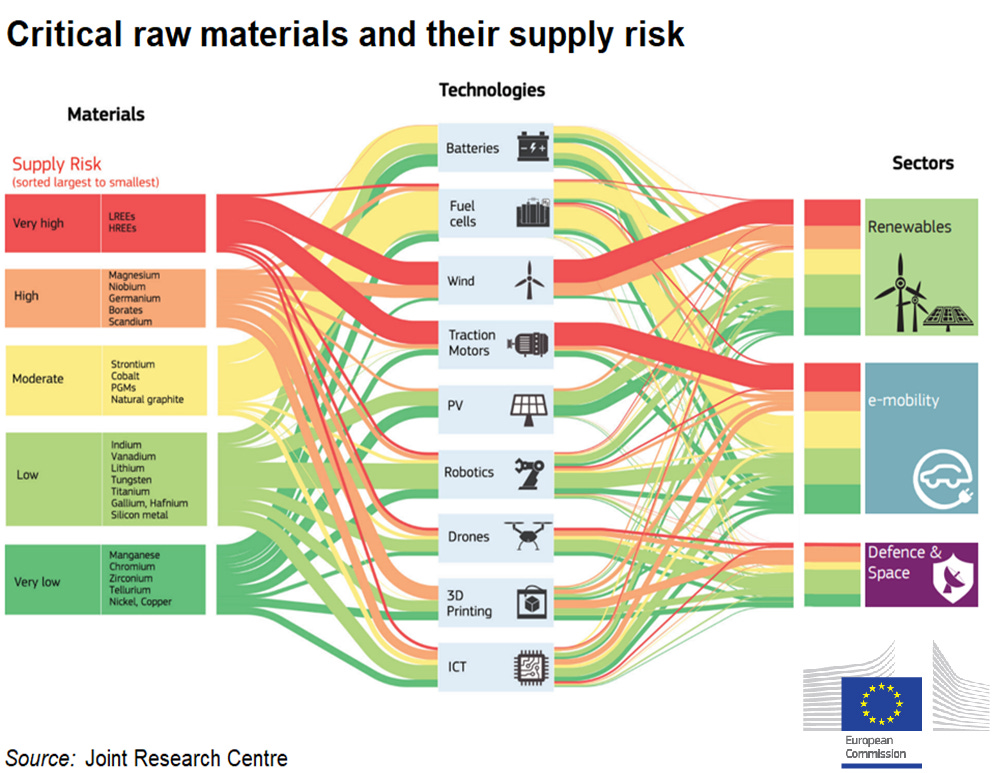
Critical minerals — rare earths like neodymium and dysprosium, plus gallium, germanium, tungsten, lithium, cobalt, and graphite — are the physical inputs behind modern industry. EV motors, wind turbines, semiconductors, and precision weapons systems all depend on them, most with no viable substitute at any scale that matters.
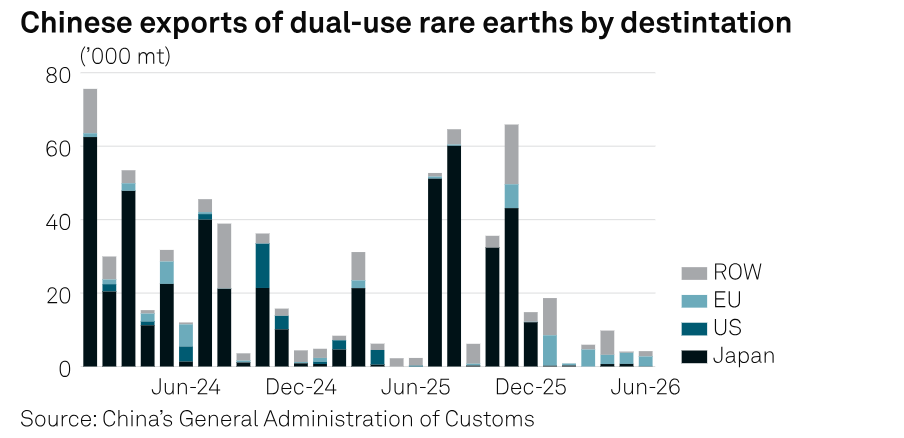
“Dual-use” simply means the same shipment can serve a civilian or a military end. Neodymium-praseodymium magnets go into EV motors and missile guidance systems. Gallium and germanium go into solar cells and into the infrared optics on military sensors. Tungsten goes into cutting tools and into armor-piercing rounds. That overlap is precisely why these materials make such an effective lever in a trade dispute: restricting them is never just a trade move.
For Europe, the real problem isn’t mining. It’s refining
Europe’s exposure isn’t really about who owns the ore. It’s about who can turn ore into usable material. China controls 85–90% of global rare earth processing capacity and supplies 48% of the world’s processed lithium-ion battery materials. Even where Europe or its allies hold raw deposits, there’s often nowhere outside China to refine them.
China controls 85–90% of global rare earth processing capacity and supplies 48% of the world’s processed lithium-ion battery materials.
The numbers on EU dependence are stark: 98% of rare earth inputs and 97% of magnesium imports come from China, and China accounts for roughly 60% of the EU’s wider critical-minerals basket. In February 2026, the EU’s own auditors concluded the bloc is “unlikely to succeed in time” on its 2030 diversification targets. That’s not a minor miss, it’s an acknowledgment that the current strategy is running on the wrong clock.
In February 2026, the EU’s own auditors concluded the bloc is “unlikely to succeed in time” on its 2030 diversification targets.
Two other facts make this worse. First, most European companies haven’t actually diversified their sourcing yet, and many have resisted sharing the supply-chain data regulators need to track progress. This is a corporate execution problem as much as a policy one.
Second, funding is thin: RESourceEU’s roughly €3 billion by 2029 has been called “far short of what is required,” especially against the US, which has announced over $30 billion in project support since early 2026 and is building a $12 billion strategic reserve. Gulf states are now bidding for the same supply too. Europe is effectively racing China as well as its own allies for scarce capacity.
What Europe actually has in place
To be fair, the framework exists. The Critical Raw Materials Act (2024) sets 2030 targets: 10% domestic extraction, 40% domestic processing, 25% recycling, and a cap of 65% reliance on any single country for one material. RESourceEU layers on a Raw Materials Platform for joint purchasing, a European Critical Raw Materials Centre for market intelligence, and new restrictions on exporting magnet and aluminium scrap to keep recyclable material inside Europe. On the alliance side, the EU has signed 14 new trade deals, struck a trilateral arrangement with the US and Japan in February 2026, and leans on partnerships with the DRC (cobalt) and South Africa (platinum group metals), though governance risk in both is real.
The problem is speed. Permitting, financing, and environmental approval all take years; but China’s leverage is being exercised now.
Europe’s options that could actually move the needle this year
Three levers don’t require new mines and could show results within 2026:
Stockpiling. The EU has shortlisted tungsten, rare earths, and gallium for a pilot reserve going operational in early 2026, with magnesium, germanium, and graphite as likely additions. This is emergency cover, not independence, but it buys time during exactly the kind of shock the July 24 export ban represents.
Joint procurement. European buyers are currently paying roughly five times Chinese domestic prices for gallium and heavy rare earths, and nearly three times for germanium. Grouping demand through the Raw Materials Platform won’t fix the supply problem, but it improves negotiating leverage immediately, without waiting for a single new refinery.
Recycling enforcement. Restricting the export of magnet and aluminium scrap, with copper likely to follow, keeps materials that are already inside European borders from leaving. It’s the closest thing to a shovel-ready policy Europe has.
The hard truth: China has Europe under control
Even in the best case, the ex-China rare earth supply chain, led by Lynas in Malaysia and MP Materials in the US, is only expected to reach about 15–17% of global NdPr (high-purity rare earth compound essential for the manufacturing of motors, actuators, and generators) demand once current projects mature, and heavy rare earths (dysprosium, terbium) won’t see real Western independence before 2028. For gallium, germanium, tungsten, and magnesium, there is essentially no non-China processing at meaningful scale yet.
For gallium, germanium, tungsten, and magnesium, there is essentially no non-China processing at meaningful scale yet.
That’s the real story behind Europe’s mineral strategy: not that it lacks a plan, but that the plan is built for 2030 while the pressure is arriving right now, in 2026. Stockpiles and joint buying can soften the next shock. They can’t yet replace the chokepoint.